The Hidden Cost of Being the Person Who Handles Everything |
Supporting a family can stretch both your salary and your time. Making those commitments visible is a practical first step towards sharing the load. |
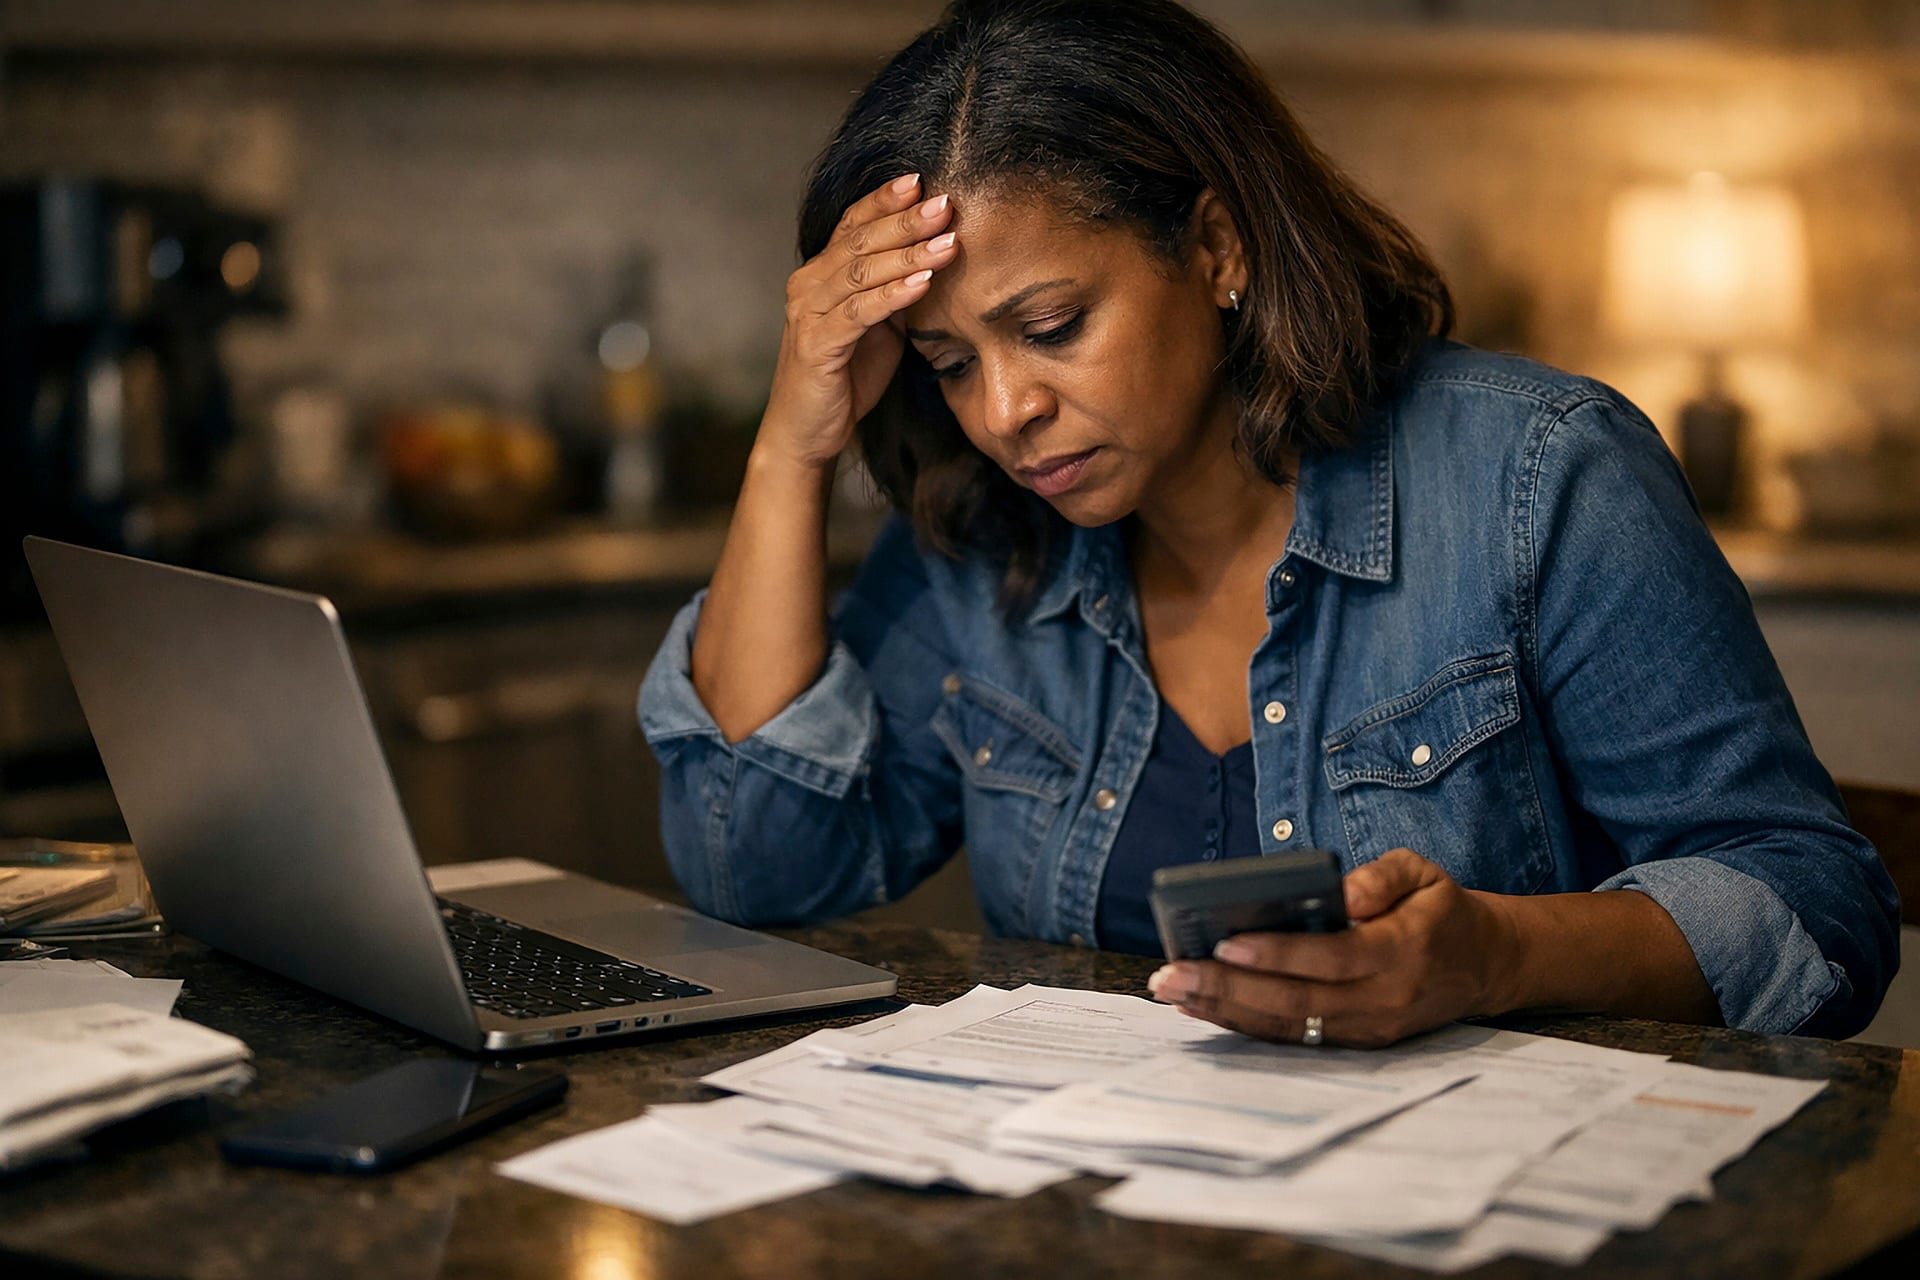
Paying the electricity bill is easy to spot on a bank statement. Remembering to buy electricity, checking the balance, and finding money when it runs out are responsibilities that rarely show up anywhere.
Add school arrangements, groceries, care for relatives and requests for financial help, and running a household, and it can become a second job.
Women carry most unpaid domestic and care work worldwide, according to the World Bank. Although anyone can become the person everyone relies on, that uneven distribution helps explain why conversations about women’s finances need to include responsibilities beyond their own spending.
Practical steps can make those responsibilities clearer and help you agree on what is manageable.
Put Family Support Into the Budget
Regular transfers are only part of the picture. Buying groceries for a parent, paying a relative’s transport or covering someone’s airtime also comes out of the same income.
Review your recent statements and list:
ASISA’s consumer education initiative, Smart About Money, recommends budgeting for all income and expenses, including savings and protection against financial risks.
Seeing the full amount makes it easier to decide what you can continue offering. If essential expenses already exceed income, a budget can expose the shortfall, but it cannot create the missing money.
Agree on Support Before the Next Request
Standard Bank’s guidance on financial boundaries recommends understanding what your budget allows, setting limits on lending and giving, and communicating those limits clearly.
A practical conversation can cover:
For example, you could explain: “I can contribute this amount towards groceries each month. Any additional expense needs a discussion first.”
This is suggested wording, not a rule about how families should support one another. Each household’s needs and resources differ.
Share Responsibility for the Tasks Too
Financial contributions do not account for all the work involved in keeping a household running.
Make a short list of recurring tasks, including shopping, school communication, appointments, transport and bill administration. Where other household members can contribute, agree who will take responsibility for each task from start to finish.
That includes remembering the deadline, making the arrangements and following up.
Someone who cannot contribute more money may still be able to collect medicine, prepare meals or handle an administrative task. Agreeing on specific responsibilities gives everyone a clearer understanding of the work involved.
Make Room for Your Own Financial Needs
When money is tight, personal savings or insurance payments may seem easier to postpone than an immediate family request.
Before changing those commitments, check the consequences. Smart About Money warns that stopping insurance premiums can leave you and your family exposed to financial risks, even when there is no immediate visible effect.
Review what you can afford and seek appropriate advice before cancelling cover or changing retirement arrangements. Avoid promising support on the assumption that you will somehow find the money later.
If debt repayments have become unmanageable, consider speaking to a registered debt counsellor about your circumstances. Check their registration through the National Credit Regulator’s register before proceeding.
The Bottom Line
Start with one conversation and one written list: what you pay, what you organise and what others can take responsibility for.
You do not need to solve every household pressure at once. A clear agreement gives the next request a starting point beyond the assumption that you will handle it. |
More from Joburg Insider
Nov 6, 2026
Funding Helps a Local Product Reach Launch
The Gauteng launch highlights support available to help South African businesses bring locally developed products to market.
Nov 6, 2026
Answers Sought on Mayibuye Roadworks
Community leader raises congestion and emergency-access concerns over Sinamurula Street works.
Oct 27, 2026
Stretch Your Fuel Budget Without Running Dry
You do not need a full tank every time, but planning when to refuel can help protect your car and avoid getting stranded.
0 Comments
Join the conversation
Be the first to comment
Share your thoughts above.